The Katelayna Insider
What Are All These Charges, Why Do They Exist, and Who Actually Pays Them?
I was having a conversation with my dad recently, and he started asking me questions about who actually pays what when a house sells.
We started with commissions. If a seller hires an agent to list and sell their home, the seller agrees to a listing fee. That's what they're paying the brokerage they hired to represent them and sell the property. How that money eventually gets split between the brokerage and the individual agent is a whole separate topic, and honestly probably another Insider article.
Then he asked who pays the agent representing the buyer, and that's where we got into something I don't think nearly enough people understand.
A seller can agree to compensate the brokerage representing the buyer, and we still see that negotiated in transactions all the time. But the seller isn't automatically required to pay the buyer's agent just because that agent brought the buyer. That compensation is negotiable.
For a long time, I don't think that distinction was made very clear to consumers. The way commissions were commonly presented made it pretty easy to walk away thinking there was just a commission that came out of the seller's proceeds and somehow got divided between the agents. The major commission lawsuits brought a lot of attention to how compensation was communicated and offered, and the industry has since changed how buyer-agent compensation is handled and discussed.
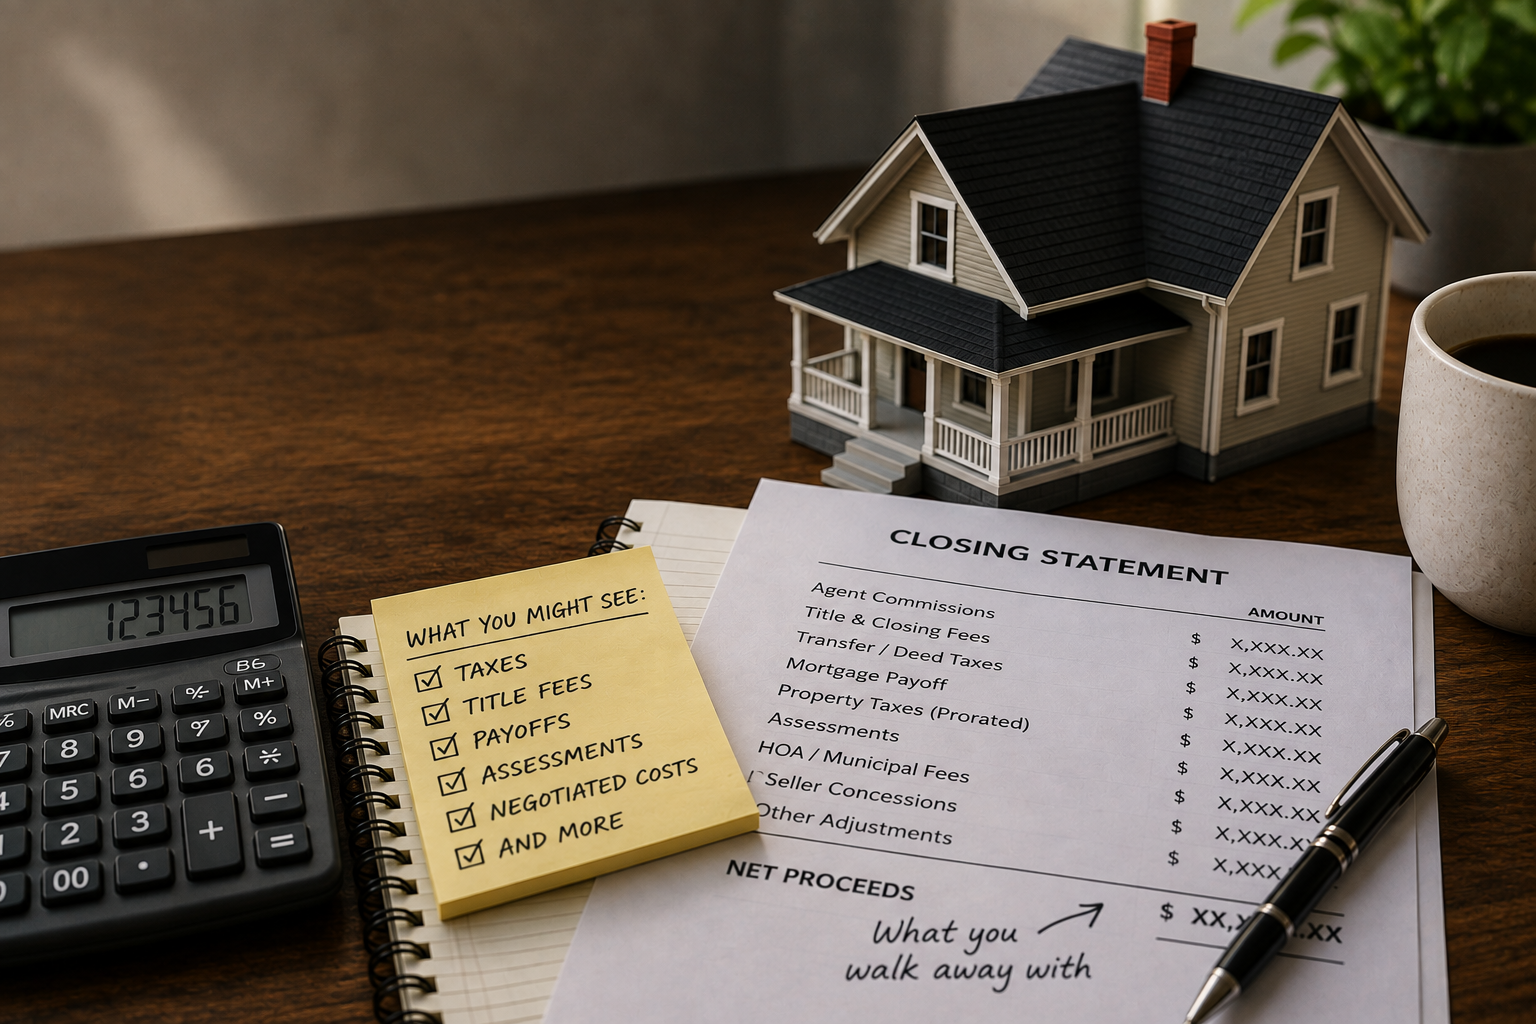
But then I started telling my dad about everything else a seller can end up seeing in a transaction. Deed or transfer taxes. Title and closing fees. Costs associated with paying off and releasing a mortgage. Property taxes. Assessments. Depending on the property, there can also be HOA charges, municipal requirements, well or septic costs, utility balances and other expenses.
He was shocked, but the part he really couldn't understand was why some of these fees existed in the first place. And that's a fair question.
When you sell a house, you're not just handing someone the keys and collecting a check. Legally, ownership of that real estate has to transfer from one person to another. The existing owner's interest has to be cleared, the new owner's interest has to be established, mortgages and other liens may have to be satisfied, documents have to be prepared and recorded, and state and local governments may impose taxes or fees on the transfer.
That's where some of these charges come from.
Minnesota, for example, has a deed tax associated with many transfers of real property. Wisconsin has a real estate transfer fee. Those aren't commissions, and they aren't fees your agent or title company decided to tack onto the transaction. They're government charges associated with transferring real estate. Who is responsible for a particular cost, though, isn't something you should assume is universal. State law, the type of charge and, where permitted, the terms negotiated in the purchase agreement can all matter.
Then there are recording-related charges. Real estate ownership isn't changed by simply crossing out one name and writing in another. Documents related to the sale have to be recorded in the public land records so there is an official record of the transfer and the interests affecting the property. Depending on the transaction, documents may also need to be recorded showing that an existing mortgage or other lien has been satisfied.
Title and closing fees are another category, and this was probably the hardest one to explain because “title fees” can sound incredibly vague if nobody tells you what the title company is actually doing.
Before a property changes hands, the title has to be examined. The title company is looking at public records and the property's ownership history to identify anything that could affect the seller's ability to transfer clear title or the buyer's ownership after closing. That can include mortgages, liens, judgments, unpaid taxes, assessments, easements and other encumbrances or recorded interests affecting the property.
And not everything they find is necessarily a problem that has to be removed. An easement giving a utility company access to part of the property, for example, may simply remain with the property after it's sold. A mortgage that belongs to the seller, on the other hand, generally needs to be paid off and properly released. Part of the title process is figuring out what is there, what needs to be resolved and what will continue to affect the property after ownership changes.
The title or closing company may also handle a significant amount of the actual closing. They can prepare or coordinate documents, collect and distribute funds, obtain mortgage payoff information, make sure existing obligations are paid, handle recording and ultimately account for where all of the money in the transaction goes. The exact services and charges vary depending on the state, company and transaction, which is why there isn't one universal “title fee.”
Property taxes and assessments can be another source of confusion because even those aren't as simple as saying, “the seller pays this and the buyer pays that.” How taxes are handled can depend on the state, when taxes are due, what period they're being collected for and what the buyer and seller agreed to in their contract. They may be prorated or handled another way based on the terms of the transaction. Assessments can have their own rules and negotiations as well.
That's really the bigger point. There isn't one universal list where everything on the left belongs to the seller and everything on the right belongs to the buyer.
Minnesota and Wisconsin handle some things differently. Individual municipalities can have their own requirements. The property itself can create additional expenses, and some costs are negotiable between the parties. That's why I don't like throwing out one percentage and telling sellers, “This is what closing costs will be.” It can create the exact problem we're trying to avoid.
There are also costs that come directly out of the negotiation. A buyer may ask the seller to contribute toward their closing costs or compensate their brokerage. An inspection can lead to repairs or a credit, and an appraisal can sometimes send everyone back to the negotiating table. Those aren't automatically required seller expenses. They're things the parties may agree to as part of getting the transaction to closing.
When all of these charges appear together on a closing statement, though, they can look like one giant pile of fees. They're not. Some are government taxes or recording charges. Some pay for title and closing services needed to get the property legally transferred and the money where it needs to go. Some settle expenses or obligations connected to the property. Some are compensation for the professionals the parties hired. And some are there because the buyer and seller negotiated them.
Start adding everything together and a seller can easily be looking at thousands of dollars more coming out of their proceeds than they expected.
That's the part I think matters. A good agent should be having this conversation with you before you get anywhere near the closing table. We can't predict every expense that's going to come up, and some numbers won't be known until the title work is completed or you're further into the transaction. But you should have a realistic idea of what selling your home is going to cost, why you're paying those costs and what your estimated proceeds could look like.
If you're selling a $300,000 house, the important number isn't just $300,000. It's what you actually walk away with.
That means looking at your mortgage payoff, the listing fee you agreed to, any buyer-broker compensation you've agreed to pay, seller concessions, applicable government taxes and fees, title and closing expenses, assessments and whatever else applies to your particular property and agreement. Some of those numbers are estimates and some may change along the way. That's normal. Being completely surprised by them at closing shouldn't be.
That's what stuck with me after the conversation with my dad. He wasn't really questioning whether the fees were legitimate. He wanted to understand why selling a house required all of these other people, taxes, documents and charges in the first place.
Once you understand what is actually happening behind the scenes to legally transfer a piece of real estate, the charges make a lot more sense. But nobody should expect a homeowner to just know that.
There are a lot of things in real estate that those of us who do this every day take for granted because we see them all the time. That doesn't mean the person selling their home knows them, and they shouldn't have to know what questions to ask in order for someone to explain it.
That's part of the job.